




Asian equities push higher

OVERNIGHT
Asian equity markets were higher on signs of moderation in global banking concerns and led by the Chinese tech sector after reports that Alibaba will be reorganised (split into six units). Overnight, Australia February CPI fell more than forecast to 6.8% from 7.4%, supporting the case for the RBA to pause hiking. Yesterday, US consumers appeared to shrug off recent banking woes after consumer confidence unexpectedly increased.
THE DAY AHEAD
It is likely too early for any impact of the recent global banking concerns to be reflected in this morning’s BoE money and credit data, but the potential impact on credit conditions and the economic outlook will be closely watched by policymakers in the coming months. We expect net consumer credit to have risen by £1.2bn in February compared with £1.6bn in January. The number of mortgage approvals probably picked up to around 42k from 40k which would be the first month-on-month rise since August.
Early this morning, German GfK consumer confidence rose to -29.5 from -30.6, the sixth monthly increase in a row. There are otherwise no major releases today from the bloc with focus instead on ECB speakers Kazimir and Schnabel. The latter will discuss the outlook for inflation at the NABE conference. The ECB has signalled it is likely to raise interest rates again to bring inflation lower if market tensions continue to ease. The first indications of March inflation will come tomorrow from Germany and Spain ahead of the Eurozone flash estimate on Friday.
Today’s US pending home sales for February are expected to show a fall but the focus, as in the Eurozone, will be on inflation data at the end of the week with the release of the Fed’s preferred gauge, the PCE deflator. In both the Eurozone and the US, headline year-on-year inflation rates are forecast to fall but core inflation is expected to rise again which will keep policymakers on alert.
This evening the BoE’s Mann, who has generally been the most hawkish MPC member, is scheduled to speak on ‘inflation and monetary policy’ at the NABE conference.
MARKETS
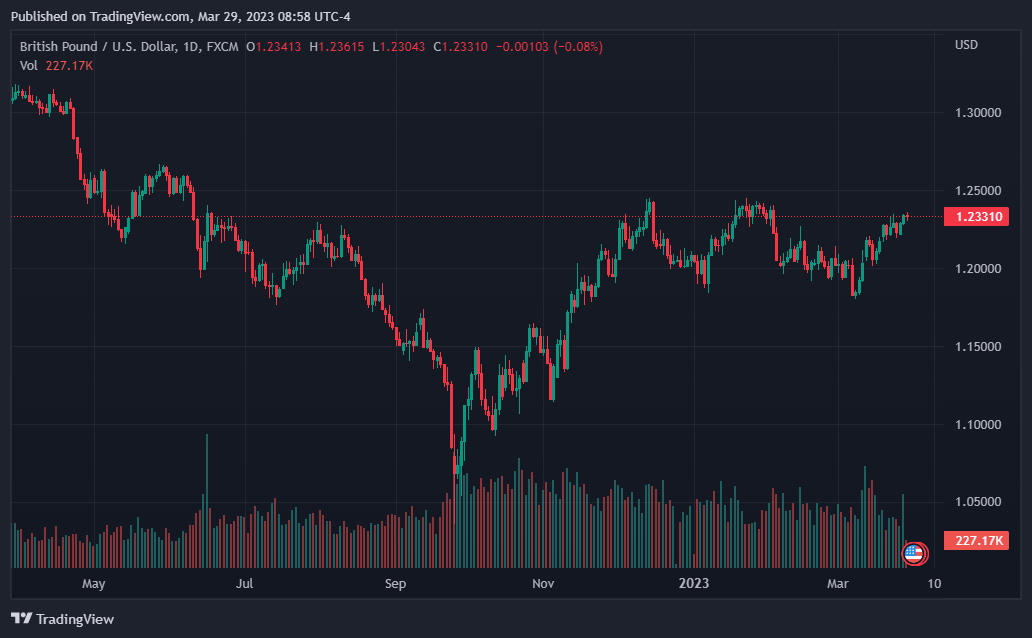
The US dollar was slightly firmer overnight after hitting latest lows. As a result, GBPUSD edged down towards 1.23 and EURUSD was closer to 1.08. US 10-year Treasury yields were little changed while oil prices climbed. UK 10-year gilt yields closed higher yesterday. Market pricing suggests expectations for a BoE quarter-point hike by June have been reinstated.
US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026
The dollar saves the day
Tech Stocks Lead US Selloff Ahead of Payrolls
The euro has spread its wings
GBPUSD bull run: Can the pair smash through 1.3565?
Democrats' Midterm Victory Sends Dollar and Oil Lower
US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback