

US CPI IN FOCUS

OVERNIGHT
President Biden signed an executive order restricting some US investments in China, including into technology surrounding semi-conductors and artificial intelligence. Chinese equity markets fell on the news. Energy commodity prices rose with oil prices nearing a 2023 high and gas prices surging the most since early 2022 following news of possible industrial strikes in Australia impacting around 10% of global LNG exports. Meanwhile, the UK RICS house price balance fell to -53 in July, its lowest since March 2009, reflecting subdued demand in the domestic housing market.
THE DAY AHEAD
The focus of today will be on US CPI, released at 13.30 BST, financial markets will be keenly watching for any signals that help clarify the interest rate outlook following the mixed labour market report last week. Despite US CPI inflation dropping to 3%y/y in June, we expect July’s reading to show a modest rise to 3.3%y/y driven by unfavourable base effects from the year prior. However, the month-on-month change in prices is expected to keep the soft-landing narrative intact, we look for 0.3%m/m, marginally higher that the market consensus of 0.2%. Gas prices have seen a renewed shift higher recently, and while much of this effect is likely to be evident in next month’s (August) CPI, it creates an upside risk for today’s m/m release.
More broadly, the move in oil prices and renewed concerns over food security heading into the second half of the year, means we may have already seen this year’s low for headline inflation. For ‘core’ inflation, last month’s slowdown to 4.8%y/y was driven by only a few areas of the basket and therefore likely exaggerated the decline. As such, we look for a small reversal to 4.9%y/y in July. However, and in contrast to the headline rate, core price inflation is expected to fall further in the second half of 2023.
While there are no data releases in the UK today, early tomorrow sees the release of GDP data for the month of June and for the second quarter overall. We expect a monthly rise in June (+0.3%m/m) with output boosted by an additional working day in the month relative to May. Such an outturn would be sufficient to result in a quarterly rise of 0.1%q/q for the second quarter and in line with BoE projections. However, the second half of the year is expected to be less benign. Regardless, the BoE marginally raised its expectations for economic growth in 2023 overall to 0.5% from 0.4% in their May forecasts.
MARKETS
Market moves today will likely be driven by developments in the US. Hopes that today’s US CPI release will support the end of the Fed’s monetary tightening cycle is helping to drive some US dollar weakness in early trading. US treasuries yields are also dipping slightly reversing some of the 6bp increase in 2yr US Treasury yields seen in yesterday’s session.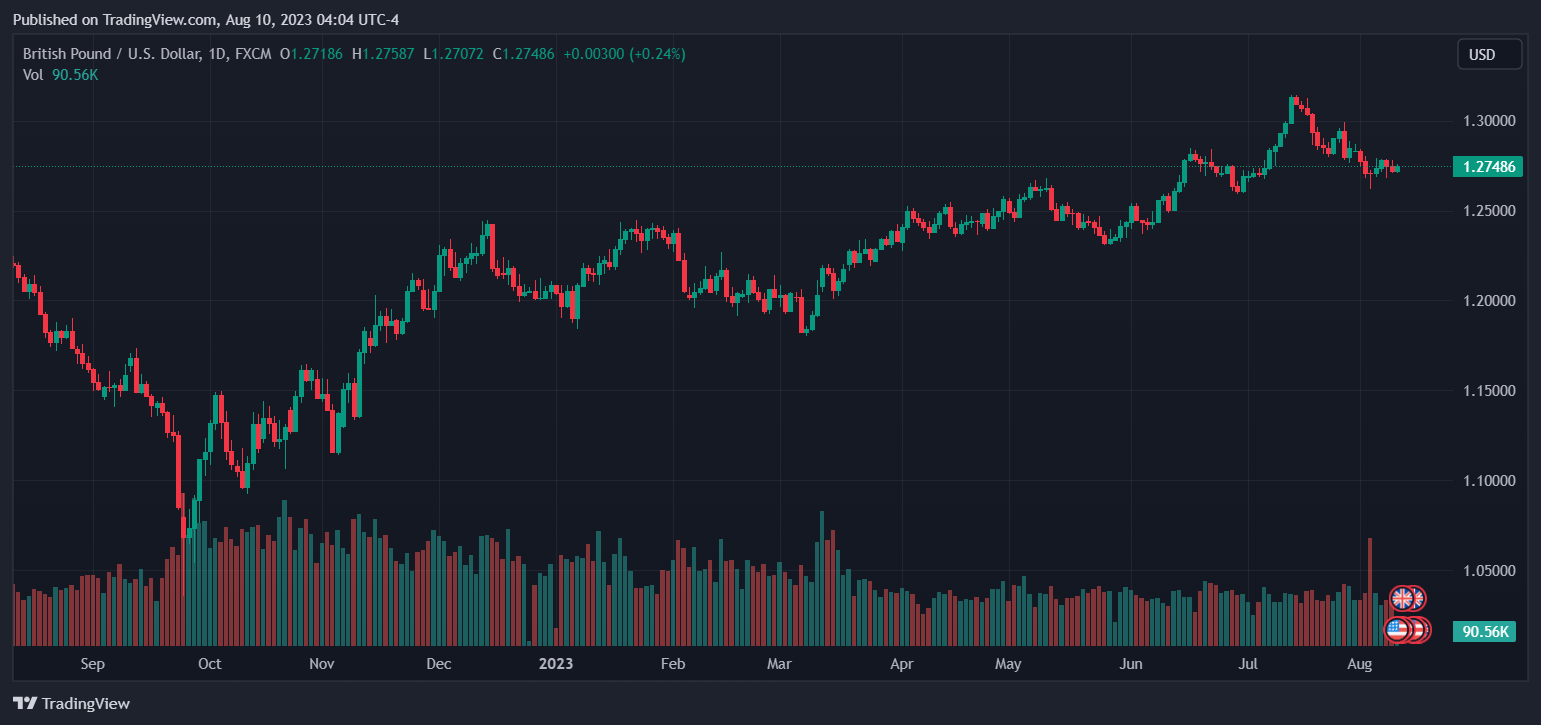
BITCOIN CRASHES BELOW $60,000: MAXIMUM PAIN AND THE THREAT OF MASS LIQUIDATIONS
The yen capitalised on the flight from risk
Crypto market retreats to $2.11T, following stocks
Stocks sink despite record Anthropic IPO, gold dives, dollar shines
Weekly Market Recap and Forecast: Anthropic Makes Nasdaq Debut in Record IPO Despite Tech Sell-off. Gold Falls Toward $3,500 levels
Week Ahead – Flash PMIs and PCE inflation in focus ahead of Thanksgiving
AI Selloff Deepens Despite Anthropic’s Record Debut